Compare coverage before comparing prices
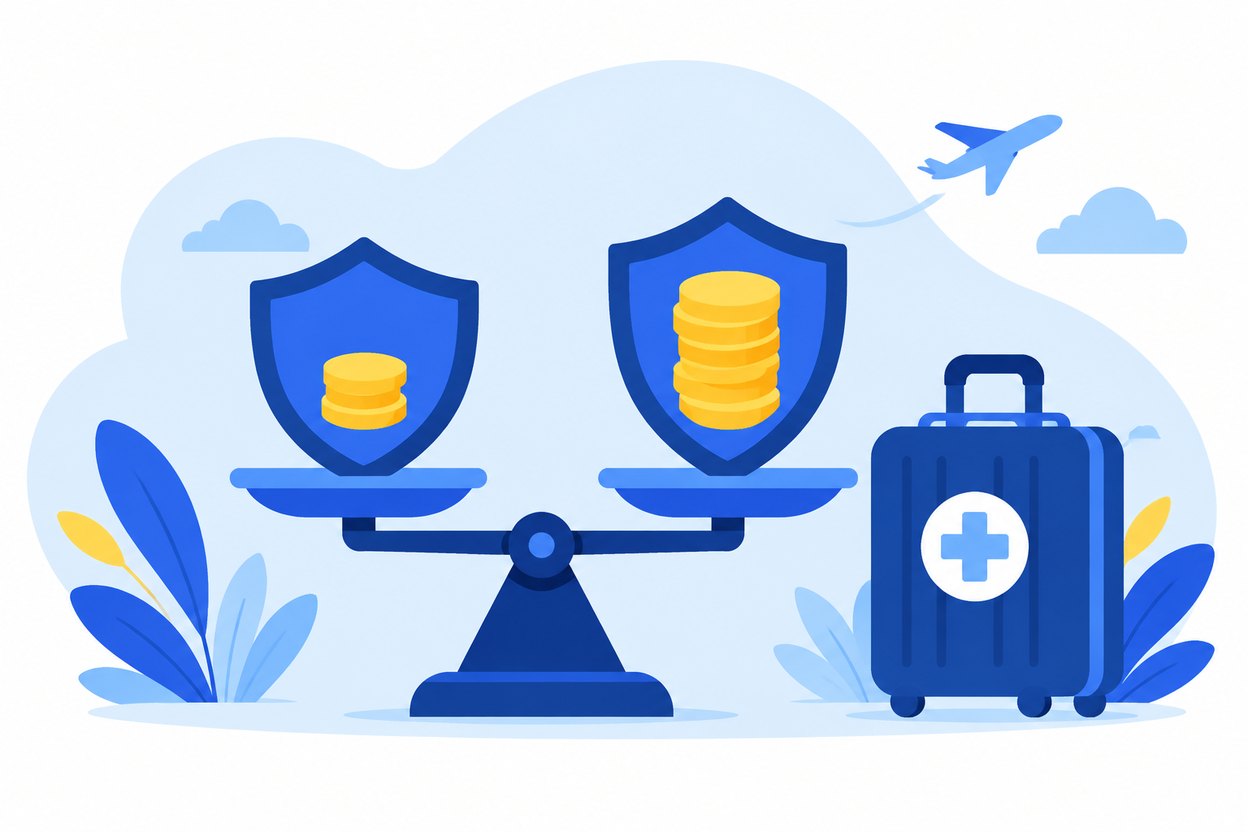
A policy premium is paid whether or not you claim, while an excess is the amount you contribute to an eligible claim. Enter quotes for the same traveler, destination, dates, and coverage level. The calculator adds each premium to its excess multiplied by your expected number of claims. An expected claim count can be fractional when you are exploring a probability-weighted scenario, rather than predicting a specific number of incidents.
Use the result to organize the next decision, then verify the details against your own documents and itinerary. Save the assumptions you entered so that you can repeat the comparison if your dates, prices, or travel arrangements change. A calculator cannot see restrictions buried in a booking confirmation or policy wording. When an input is uncertain, try a conservative alternative and look at whether the outcome changes enough to affect what you book.
Interpret the result as a scenario, not a recommendation
For example, a US$50 premium with a US$100 excess costs US$150 in a one-claim scenario, while a US$90 premium with a US$25 excess costs US$115. With no claims, the lower premium wins instead. The comparison assumes the full excess applies to every claim. Actual payments depend on eligible losses, section-specific excesses, policy limits, and whether multiple claims are treated as a single event.
Before acting, review the result with the person responsible for the booking and check any relevant provider instructions. Keep a copy of important confirmations available offline during the trip, especially when internet access may be unreliable. If your circumstances differ from the simplified assumptions explained above, adjust your plan rather than treating the displayed answer as a requirement. The most useful estimate is one you can trace back to realistic inputs and update when something changes.